How Car Dealerships Can Mitigate Fraud
Car dealership fraud prevention is critical as auto loan fraud surged to $7.7 billion in 2021, driven largely by synthetic identity fraud—which comprises 80–85% of identity fraud cases—and dealerships face significant financial, legal, and reputational risks from forged documents and falsified buyer information, necessitating comprehensive process and technology solutions throughout the sales lifecycle.
New
Proof launches portable digital identity for banks
Introducing portable identity

Updated September 8, 2026
Car dealership fraud prevention starts with one uncomfortable fact: auto loan fraud hit $7.7 billion in 2021, up 267% since tracking began in 2010, according to Point Predictive's Auto Fraud Trends Report. Lenders are responding by requiring dealers to buy back deals tied to identity theft. That means the financial exposure lands directly on your lot.
At the center of nearly every fraud case is the same vulnerability: identity. Synthetic identity fraud, where thieves combine real and fabricated information to create a false but convincing identity, now accounts for 80–85% of all identity fraud according to the Federal Trade Commission (FTC). These fabricated identities carry real credit histories and real scores. There is no real person behind them, which is exactly what makes them so difficult to catch.
Forged documents, falsified vehicle histories, and misrepresented buyer identities add layers of risk to every transaction. One oversight can become a six-figure mistake and expose your dealership to regulatory action, reputational damage, and legal liability. Staying ahead of fraud requires deliberate process and technology across the full deal lifecycle.
Key takeaways
- Auto loan fraud reached $7.7 billion in 2021, a 267% increase since tracking began in 2010, and synthetic identity fraud now accounts for 80–85% of all identity fraud cases.
- Many lenders now require dealers to buy back deals linked to identity theft, meaning fraud losses fall directly on the dealership.
- Credit report discrepancies, multiple hard inquiries in a short window, and mismatched buyer documents are primary indicators of fraud at the application stage.
- Digital identity verification tools, including document capture, biometric comparison, and session recording, give your team evidence to make confident decisions and create a defensible audit trail.
- Effective car dealership fraud prevention requires layered defenses: technology and human judgment working together from the first credit application through the final signature.
- Fraud penalties in auto transactions can reach three times the vehicle's value, making a verifiable record of every authorization a business necessity.
Why car dealerships are prime fraud targets
Dealerships sit at the intersection of high-value assets and complex, multi-party financing. Every new loan creates two simultaneous risks: loss from fraud associated with the applicant, and exposure to regulatory non-compliance if your verification process fails.
The digital shift in auto retail has expanded the attack surface. According to a 2021 Cox Automotive study, 96% of car buyers are open to applying for financing online, and one in five completes more than half of their purchase process digitally. Fraudsters know this. They also know that most fraud investigations happen after the deal closes, not before.
Experian's automotive fraud research confirms the scale: 84% of auto lenders report suspected or confirmed auto loan fraud in the past year, and the average dealer completes four fraudulent deals before detection. By then, the financial damage is done.
The three types of fraud hitting dealerships
Understanding how fraud is structured helps your team recognize it earlier in the process.
First-party fraud occurs when a real person deliberately misrepresents their own information to obtain financing or goods. Credit washing is a common example in auto retail: individuals falsely claim identity theft to wipe negative items from their credit reports, leaving lenders and dealers underwriting a consumer based on inaccurate data.
Third-party fraud, commonly called identity theft, occurs when someone uses another person's personal information without their knowledge. Stolen names, Social Security numbers, dates of birth, and addresses are combined with fake documents to impersonate a legitimate buyer. The victim typically has no idea their identity has been compromised until they notice suspicious activity on their credit report.
Synthetic identity fraud is the most difficult to detect. It begins with a stolen piece of real information, such as a Social Security number, then combines it with fabricated details to create an entirely new identity. These synthetic identities are built to look legitimate: fraudsters often spend months establishing a credit history before attempting a high-value purchase. Standard identity verification methods are designed to flag mismatches, not fake people.
Document red flags your team should catch
Credit reports are one layer. The documents your buyers present, including driver's licenses, proof of income, and proof of residence, are another. Falsely represented identities and forged supporting documents are common tactics in auto fraud.
Common document red flags:
- Driver's license photos that do not match the person in front of you, or IDs with inconsistent formatting, fonts, or holograms
- Proof-of-income documents that appear altered: mismatched fonts, rounded figures, or employer details that do not check out
- Vehicle history reports that conflict with the physical condition of a trade-in, or title documents with signs of tampering
- Address or name discrepancies across the buyer's submitted paperwork
- Employer details that are vague or cannot be verified
If any document looks altered, or if details do not match across the buyer's paperwork, pause and verify before the deal moves forward. No deal speed justifies skipping this step when the buyback risk falls on your dealership.
Behavioral signals that indicate fraud risk
Your sales team is often the first line of defense. Certain customer behaviors are worth noting and escalating.
Customers who seem impatient or evasive are worth watching. Purchasing a vehicle is a significant financial decision for most people. A buyer who shows no interest in the car's features, stays on their phone throughout the process, and pushes to close as fast as possible may be coordinating with partners off-site.
Sales that seem too easy are also a signal. A customer with excellent credit who accepts the purchase price and finance terms without any negotiation, and who wants to finance 100% of the purchase price, fits a pattern worth scrutinizing.
Buyers who arrive knowing exactly what they want without looking around are not automatically suspicious, but combined with other red flags, this behavior is worth noting. Someone planning to buy with another person's information has likely pre-selected the vehicle.
These behavioral signals do not prove fraud on their own. They are indicators that warrant additional verification before the deal closes.
Car dealership fraud prevention through digital identity verification
Identity theft and document fraud do not stand still. Fraudsters refine their methods continuously, from sophisticated synthetic identity fraud to AI-generated documents that pass visual inspection. The right technology gives your team the evidence they need to make confident decisions.
Digital identity verification tools address the core weakness in manual processes: a trained eye can be fooled, but a layered verification system catches what humans miss.
What a strong identity verification stack includes:
- Document capture and authentication: High-resolution scanning that reveals hidden security features like watermarks, holograms, and UV-reactive ink, then compares data against official templates to detect anomalies in fonts, spacing, or design elements
- Biometric comparison: Matching the selfie a buyer submits against the photo on their ID to confirm the person presenting the document is the person it belongs to
- Database cross-referencing: Comparing applicant-provided information (name, address, date of birth, Social Security number) against government databases, credit bureaus, public records, and watchlists
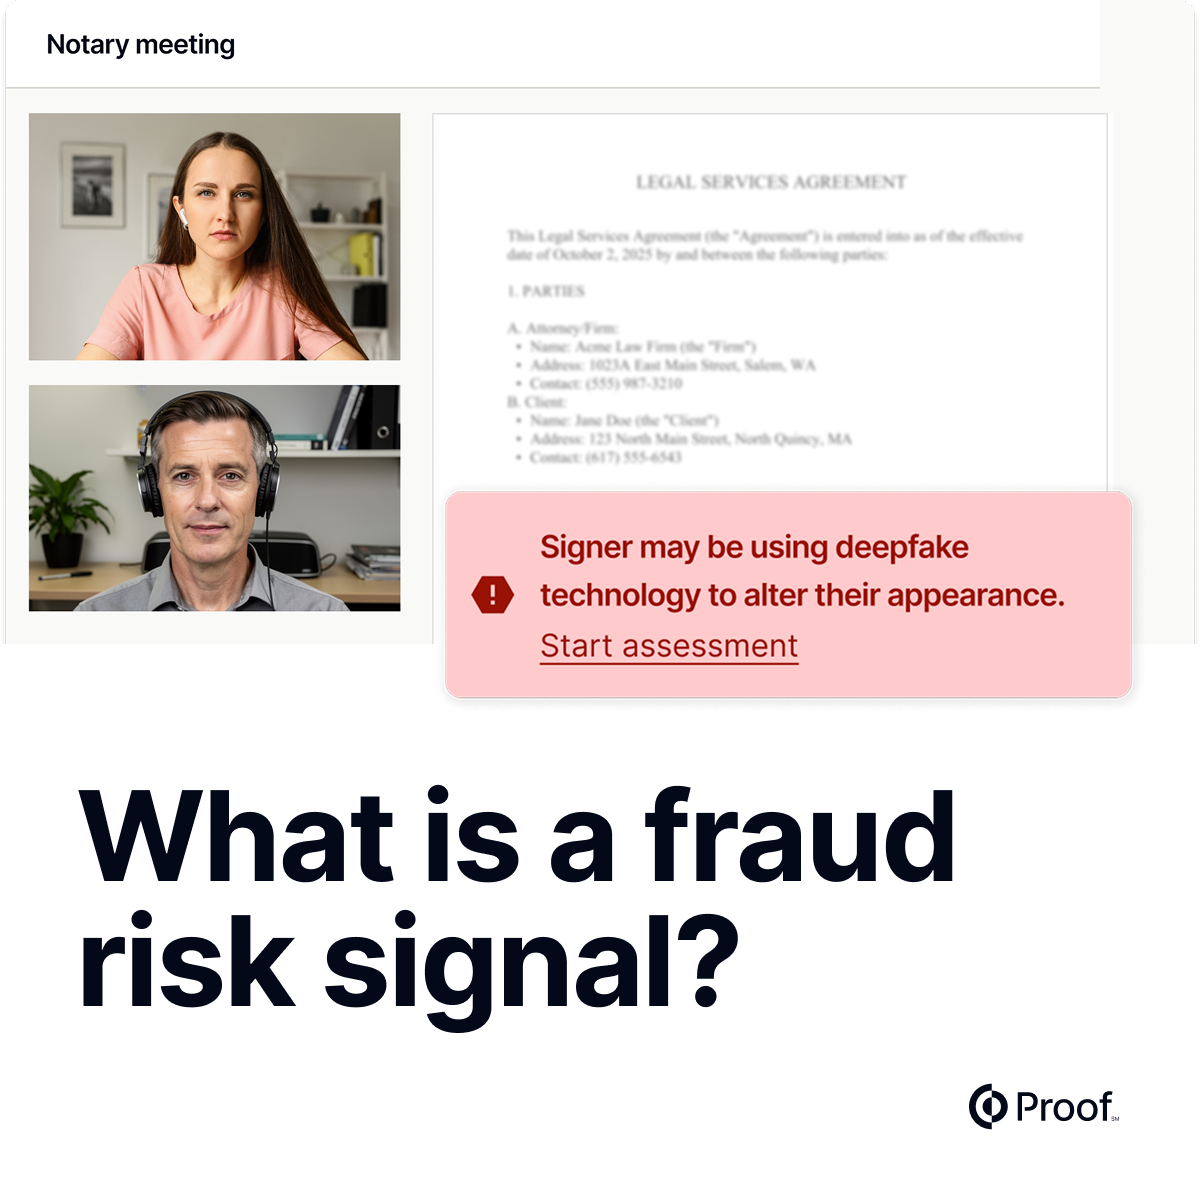
- Fraud scoring: Real-time risk assessment that flags inconsistent information, high-risk behaviors, or known fraud indicators before the deal closes
- Session recording and audit trail: A comprehensive, readily available record of the verification process for your dealership and any lender dispute
Many dealers already require the notarization of limited powers of attorney (POAs) to register the title on behalf of the buyer. Notarize by Proof builds identity verification directly into the notarization workflow, capturing and storing the signer's identification document, recording the full notary session, and generating an audit trail that documents every step.
When fraud-related penalties in auto transactions can reach three times the vehicle's value, having a defensible, verifiable record of every authorization is protection, not overhead.
Building a fraud-resistant process across the deal lifecycle
Technology alone does not stop fraud. Process and training determine whether your team uses the tools correctly and consistently.
Formalize a risk escalation process. Define who reviews flagged cases, what investigative steps to take, and what additional checks to perform when a transaction is flagged. Document how to communicate with flagged individuals clearly and respectfully. Update the process as new schemes emerge.
Integrate checkpoints into your sales workflow. The FTC's Red Flags Rule requires dealers to develop a written identity theft prevention program. Build verification steps into each stage of the deal: credit application, document review, signing, and title work. For vehicles sold online or to customers who never visit the lot in person, apply additional verification before delivery.
Train staff consistently. New employees should complete fraud awareness training during onboarding, with annual refresher sessions. Training should cover what synthetic fraud is and how it differs from traditional identity theft, how to use verification tools correctly, what red flags to escalate, and how to handle flagged cases without creating a poor customer experience for legitimate buyers.
Build a culture of shared responsibility. Fraud prevention cannot rest on one person's shoulders. Every member of your team who touches a deal should have a working knowledge of red flags and know who to contact when something looks wrong.
The records that protect you after the deal closes
A fraud incident that gets through your defenses does not have to become an uncontested loss. The quality of your documentation determines how defensible your position is when a lender demands a buyback or a regulatory body opens an inquiry.
Cryptographically signed, verifiable records of identity verification, document signing, and notarization sessions give you evidence that the transaction was conducted properly. A session recording from a remote online notarization, combined with a credential analysis report and a biometric match, creates a record that is difficult to dispute.
Proof's platform covers the full deal lifecycle. Identity verification, fraud-protected eSignatures, and cross-platform fraud detection let dealerships layer defenses from the first credit application through title registration. Each product generates records that document what was verified, when, and by whom.