The Impact of Verified eSignatures on the Automotive Industry
The article discusses how verified eSignatures are transforming the automotive industry by preventing identity theft and document tampering in the rapidly growing online car sales market—where digital transactions surged from 2% to 30% in 2020—by securely linking signer identity, intent, and signature events to ensure legal compliance and fraud prevention throughout the fully digital car-buying process.
New
Proof launches portable digital identity for banks
Introducing portable identity

Updated September 8, 2026
Online car buying is a fraud magnet, and most dealerships are not ready. Every document signed remotely, every financing application submitted from a phone, and every out-of-state deal is a window for identity spoofing and signature forgery. As the car-buying journey goes fully digital, the exposure grows with it. Verified eSignatures for car dealerships are how operators close that gap, ensuring document authenticity, signer identity, and legal compliance in a single workflow.
Verified eSignatures offer more than convenience. They connect identity, intent, and the signature event itself, giving dealers a defensible record at every step. Here is how car dealerships can use verified eSignatures to close deals securely and keep fraud out of every transaction.
Key takeaways
- Verified eSignatures in the automotive industry protect dealerships from identity theft and document tampering by tying every signature to a confirmed identity before the document is executed, not after the deal closes.
- Online car sales surged from 2% to 30% in 2020, making secure remote signing a business necessity. In 2022, 87% of dealerships identified digitization as a core part of their business model, twice the rate from 2021.
- Unlike standard eSignatures, verified versions tie a confirmed identity to the document through credential analysis, knowledge-based authentication (KBA), and biometric comparison before any signing occurs.
- AI-generated deepfakes, synthetic identities, and spousal signing fraud are active threats in online auto retail. Platforms that combine identity verification with real-time fraud monitoring close these gaps before they become losses.
What a verified eSignature actually does in auto transactions
A verified eSignature is an electronic signature that is authenticated to ensure it was applied to a digital document by the intended signer. These signatures are legally binding under the Electronic Signatures in Global and National Commerce (ESIGN) Act and the Uniform Electronic Transactions Act (UETA), and can take the form of any sound, symbol, or process applied with the intent to sign.
Many tools on the market let anyone draw or type a signature image and paste it onto a document with no identity check and no audit trail. Those tools produce a mark that looks like a signature, but they offer no assurance about who placed it there. A verified eSignature closes that gap by tying the signer's confirmed identity to the document before the signature is applied.
Verification is what makes the difference. Without it, an eSignature is just a mark on a document with no confirmed connection to the person who placed it there. The verification step ties the signer's confirmed identity to the document, creating an auditable record that can withstand scrutiny in a dispute.
Do not confuse verified eSignatures with digital signatures. Digital signatures rely on certificate authorities and public key infrastructure (PKI) to authenticate a record cryptographically. Verified eSignatures confirm who signed by verifying the signer's identity in real time, at the point of signing.
Why legacy verification methods fail dealerships
Modern eSignature verification confirms the identity and intent of the signer before the signature is applied. This typically involves a combination of credential analysis (validating a government-issued ID), knowledge-based authentication (KBA) (questions derived from the signer's personal history), and biometric comparison (matching the signer's likeness to their ID). Together, these checks create a defensible record that the right person signed the right document.
Without a proper solution in place, dealerships have historically relied on workarounds that are slow, inconsistent, and difficult to defend.
-
Requiring contracts to be signed in person at the dealership under an employee's direct observation
-
Allowing remote eSigning but following up with a phone call to verbally confirm the signer's identity
-
Dispatching mobile notaries to a buyer's home to watch the signing, even when the document does not legally require notarization
-
Require identity verification at the point of signing, not as an afterthought or a post-close audit step
-
Use a platform that ties credential analysis, biometric comparison, and KBA to the signing event itself
-
Ensure every completed document includes a tamper-sealed audit trail that captures signer details automatically
These legacy methods create friction, delay the transaction, and still leave gaps in the verification record that will not hold up under scrutiny.
Fraud threats targeting online dealerships
The fundamental problem with unverified eSignatures is that they carry the same security vulnerabilities as pen-and-ink signatures. In many cases, they carry more, because the convenience of signing from anywhere also means anyone, anywhere, can apply a signature with no friction.
Verified eSignatures in the automotive industry tie every signature to a confirmed identity before the document is executed.
Common tactics:
- Stolen identity purchases: Thieves purchase vehicles online using stolen identities, applying the victim's eSignature to a contract with no friction from the dealership's system.
- Unauthorized spousal signing: A spouse signs on behalf of their partner without knowledge or consent, creating legal exposure for everyone involved.
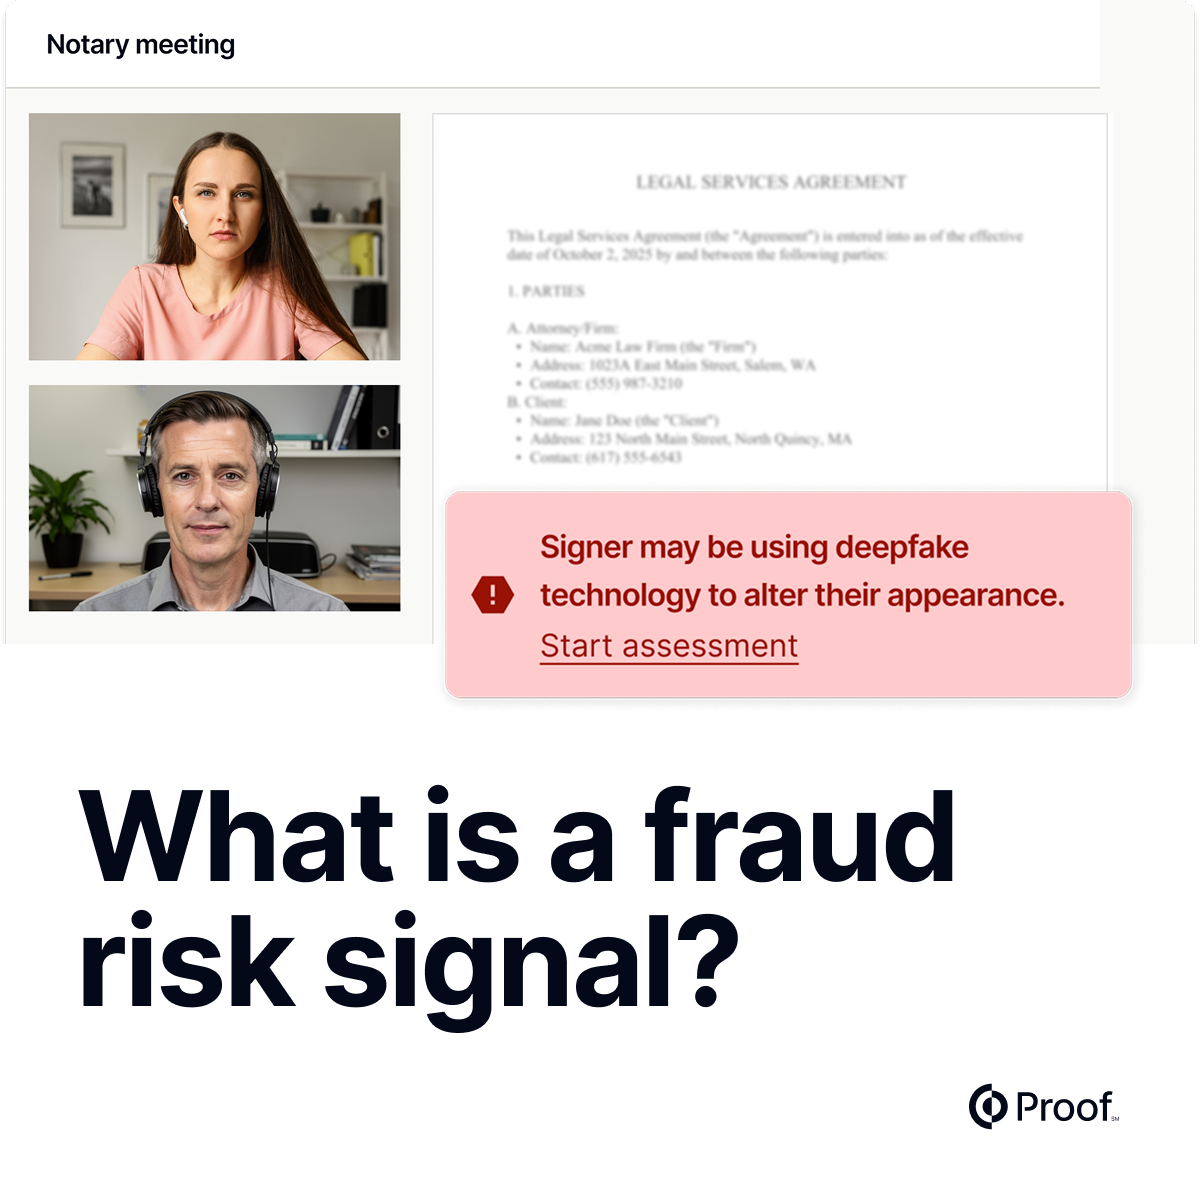
- AI-generated deepfakes: Fraudsters impersonate real buyers during remote identity checks using synthetic video, bypassing basic verification.
- Synthetic identity financing: Identities constructed from stolen data pass surface-level verification and are used to secure auto loans.
- Falsified supporting documents: Pay stubs, driver's licenses, and insurance cards are forged to support fraudulent purchase applications.
Both the first and last scenarios are preventable, but only if identity is verified before the signature is applied.
What you can do:
- Require layered identity verification before any signature is accepted, including credential analysis and KBA
- Add biometric verification with liveness detection to confirm the signer is physically present
- Use a platform that monitors for AI-generated fraud signals in real time across transaction channels
- Ensure every transaction produces a cryptographic audit trail linking confirmed identity, document version, and signature event
On the Proof platform, every completed transaction carries a tamper-sealed audit trail that captures identity verification results, fraud signals, signer biometrics, and document integrity status, all accessible from a single dealer-facing portal. You can confirm exactly who signed, when, and what the risk indicators showed at that moment.
What verified eSignatures deliver for auto deals
Verified eSignatures deliver concrete, measurable outcomes across the auto transaction lifecycle.
- Confirmed signer identity before any document is executed
- Fraud detection at the point of signing, not during a post-close audit
- Tamper-sealed documents that lock after signing, with a full audit trail
- Reduced liability from fraudulent or contested transactions
- Faster resolution when a transaction is ever called into question
Buyers have already moved online: digital showrooms, at-home test drives, home delivery. They expect the signing experience to match. If it does not, you have introduced friction exactly where deals die.
Legal compliance for verified eSignatures in auto sales
Are verified eSignatures legally valid for automotive transactions? Yes. The ESIGN Act, enacted in 2000, provides federal recognition for electronic signatures, affirming they carry the same legal weight as handwritten ones when certain requirements are met, including consumer consent and accurate record retention. UETA, adopted by most states, extends this framework to business and commercial transactions including vehicle sales and financing.
Many states that allow eSignatures on auto documents require that they be attributable to the intended signer. That means dealerships need more than a mark on a screen. They need a provable connection between the signer's identity, the document, and the signature event itself.
State-by-state nuances matter. California, for example, has delayed permanent remote online notarization (RON) adoption until January 1, 2030, though it has operated under temporary authorization. Dealers operating across state lines should confirm how electronic signatures and RON are treated in each jurisdiction before relying on a single workflow.
Verified solutions ensure documents like limited POAs meet legal standards for online notarization, which is critical for title transfers that require a notarized signature.
Security and audit trails: why they matter in disputes
A tamper-sealed audit trail is the difference between a defensible record and an open question. Every action, including document access, edits, and completed signatures, is digitally logged, timestamped, and associated with a verified user identity.
A complete audit trail for an auto transaction should capture:
- Identity verification results, including credential analysis and biometric comparison scores
- KBA completion and outcome
- Fraud risk signals flagged at the time of signing
- Document version and integrity status at the moment of execution
- Signer device, location, and timestamp data
When a transaction is disputed, this record is what determines whether the dealership or lender can defend the deal. Without it, the burden of proof falls on the party that cannot produce one.
On the Proof platform, the completed record is accessible from a centralized portal or through API integrations with existing dealer management systems (DMS) or loan origination systems (LOS).
What to require in a verified eSignature solution for auto
Look for a solution that puts identity verification at the center, as the foundation of every signature. The best platforms combine security, compliance, and speed so you are never choosing between protecting the deal and closing it fast.
Key capabilities to evaluate:
- Identity verification at the point of signing, not after the fact
- KBA that confirms the signer through questions derived from their personal history
- Credential analysis that validates a government-issued ID before the signature is applied
- Biometric comparison that matches the signer's likeness to their identity document
- Liveness detection that confirms the signer is physically present and not AI-generated
- Fraud monitoring that flags anomalies in real time
- Tamper-evident audit trails that capture every signer action and lock the document after completion
- API and DMS/LOS integration so the verified signing workflow fits inside existing systems
On the Proof platform, companies send eSign requests to their signers from a business portal, individually or in bulk using reusable document templates with pre-tagged fields. The signer verifies their identity before they can apply their signature to the document package. The completed record includes a comprehensive audit trail that captures key signer details and transaction specifics.
How dealerships are using verified eSignatures today
Dealerships have moved fast. In 2022, 87% identified digitization as a core part of their business model, twice the rate from 2021.
Verified eSignatures in the automotive industry directly secure the last mile of the purchase process: financing, contract signing, and every document that closes the deal.
Where verified eSignatures apply across the auto transaction lifecycle:
- Purchase agreements and sales contracts: Confirm buyer identity before any binding document is executed
- Financing and credit applications: Tie the applicant's verified identity to the loan document, reducing synthetic identity fraud
- Insurance disclosures: Ensure the person accepting coverage terms is the person named on the policy
- Limited powers of attorney for title transfers: RON handles notarized POAs required for title work, 24/7, without dispatching a mobile notary
- Warranty and service agreements: Protect against unauthorized signing on post-sale documents
Every unverified signature is an open question, and in auto retail, open questions become chargebacks, disputes, and losses.
How verified eSignatures speed up auto funding
One of the greatest opportunities for dealerships is around funding timelines. A Cox Automotive digitization study found that buyers prefer completing credit applications, financing qualification notifications, and insurance product selection online.
In the paper world, applying for funding and receiving approval can take days. Online platforms already offer financing decisions in minutes. Dealers still relying on manual workflows are losing deals to competitors who have already gone digital.
Every verified eSignature produces a structured, traceable record that lenders can review immediately, eliminating the back-and-forth document requests that stall funding timelines. Dealers and their lender partners can make funding decisions with confidence because every signature is backed by a verified identity and a defensible audit trail.
Proof gives dealerships a single platform for verified signing and notarization
Proof gives dealerships a single platform to verify signers, notarize documents like limited POAs, and seal every transaction with a tamper-evident, audit-ready record, 24/7, across every deal, with no gaps in the chain of trust.
Identity verification, fraud monitoring, eSign, and notarization are all in one place. The dealerships building verified eSign into their workflows now will be positioned to move faster as state adoption of eSignature legislation continues to accelerate.